Collector cars
Donate a high-value collector vehicle
Above a certain value the paperwork changes, the transport changes, and where the car is sold matters more than anything else. Here is how that works, including the part most donors are told wrong.
What changes above $5,000
Two things. You will need a qualified appraisal to claim more than $5,000, and you will file Form 8283 Section B, which the appraiser signs and which we sign as the receiving organization. We sign that form; the appraisal itself is your expense and your choice.
Here is the part donors are most often told wrong, and we would rather say it up front than let you find out in April. When a charity sells a donated vehicle, the deduction is limited to the gross proceeds of that sale. An appraisal does not lift the deduction above what the car actually brings. It substantiates the value you are claiming and it is required paperwork above $5,000, but it does not become the number.
Appraised fair market value governs only in specific exceptions: significant intervening use of the vehicle by the charity, material improvement of the vehicle by the charity, or a transfer below market value to a needy individual in furtherance of the charity's mission. Those are narrow and they will not apply to most collector cars. Assume proceeds, and treat anything better as a surprise rather than a plan.
The sale channel is where the money is
Because your deduction is the sale price, how we sell the car is not an internal matter — it is your deduction and the cause's funding at the same time. A significant car pushed through a general wholesale channel to clear it quickly is a loss on both counts.
So we do not. Depending on the car that means a specialist auction with the right catalog, a marque dealer, a registry with a waiting list of buyers, or a private sale to someone who has been looking for that exact car for two years. It takes longer. We would rather take eight weeks and sell a car properly than move it in a week and report a disappointing number to you.
We welcome your view on where it should go. You will often know the market better than we do, and you may know who has been asking about the car. What we cannot do is give you control over the sale, both because we own the car once it is donated and because a retained right over the disposition can jeopardize your deduction. Tell us what you know; the decision has to be ours.
The appraisal: who, and when
Use a marque or era specialist rather than a general automotive appraiser. On significant cars the comparable sales are few, private and specific, and someone working from a published guide cannot see them.
- The appraiser must be qualified for this kind of property and cannot be you, us, or anyone party to the sale.
- The appraisal must be dated no earlier than 60 days before the date you donate the car.
- You need it in hand by the due date of the return on which you claim the deduction, including extensions.
- Form 8283 Section B carries the appraiser's signature and ours.
Order it before the car leaves if you can. Appraising a car from photographs after it has gone is possible and is worse.
Form 8282 and the three-year window
If we sell the car within three years of receiving it, we file Form 8282 with the IRS reporting what it sold for, and you receive a copy. This is routine and requires nothing from you. We mention it because donors who have not seen it before sometimes read it as a problem when it arrives.
Transport and custody
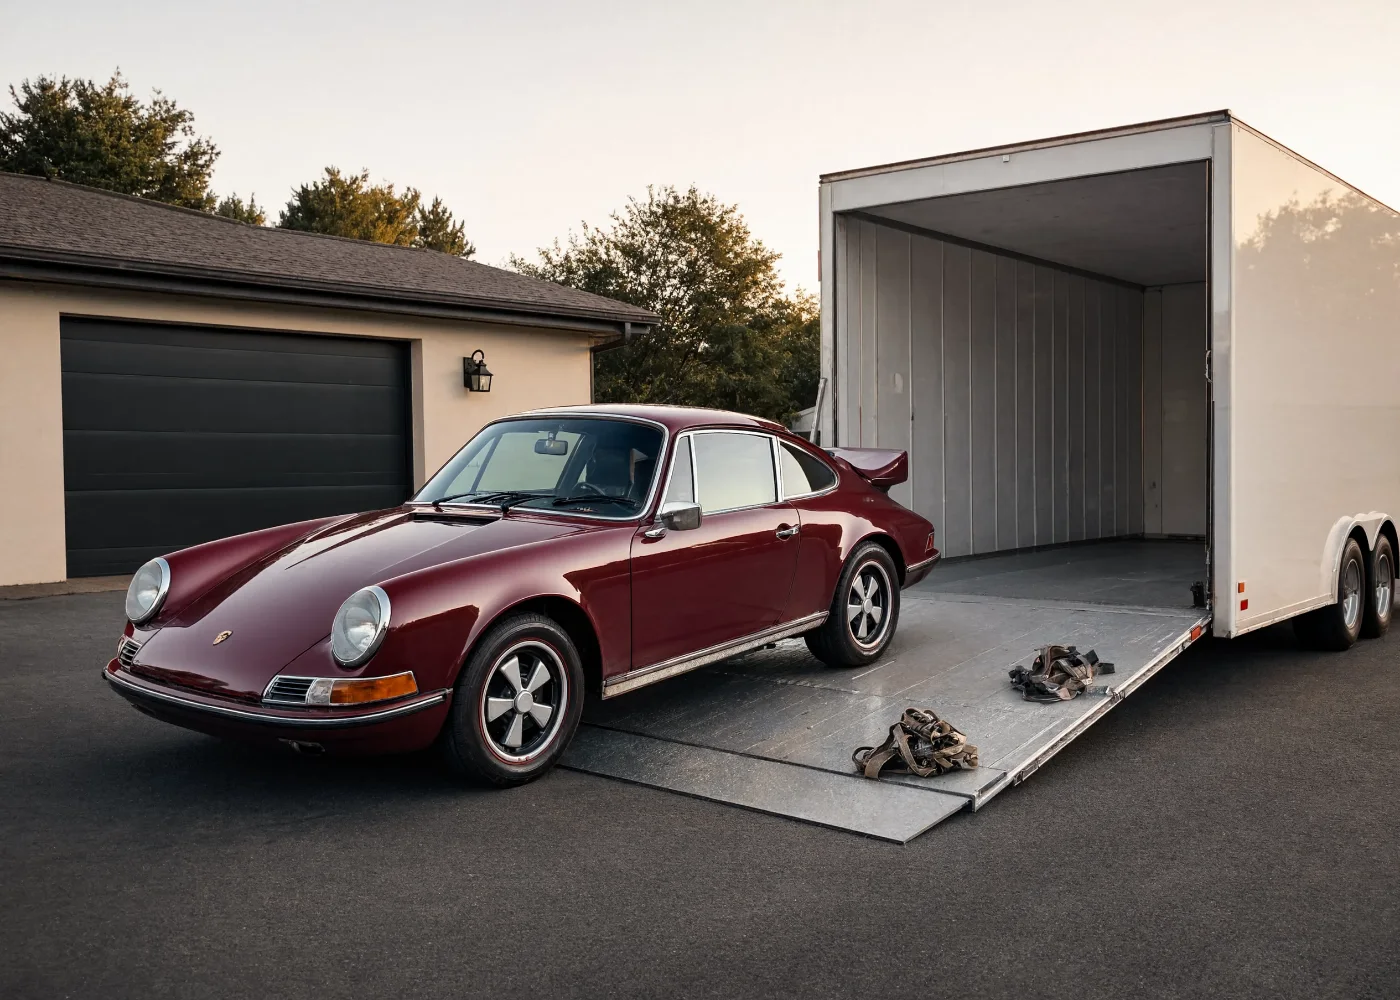
Enclosed transport, insured for the value of the car, with a named driver. The car is photographed at pickup and again at delivery, and stored under cover. If it is going to an auction, it goes direct where possible rather than through a consolidation yard.
Leave the fluids in it. Leave the battery on a tender if it is on one. Send both sets of keys, the wheel lock key and any immobilizer fob. Tell us about anything the driver needs to know: a manual choke, a battery cutoff, a clutch that needs bleeding, a ride height that will not clear a standard ramp angle.
The documentation that moves the price
On a significant car the file is worth a meaningful percentage of the sale, and assembling it is the most useful thing you can do for the cause.
- Ownership chain, ideally back to first sale, with old registrations and correspondence.
- Build records: window sticker, build sheet, factory certificate, matching-numbers documentation.
- Restoration records: who did the work, when, what was replaced, and photographs during.
- Registry certification, concours judging sheets, class awards, period magazine features.
- Everything physical that came with the car: hardtop, original wheels, jack and tools, owner's books, service manuals, spare parts you bought and never fitted.
Send the spares. Donors routinely keep a shelf of correct parts back, and the parts are worth much more attached to the car than they are on the shelf.
Privacy
We do not publish donor names, photographs of donated cars or details of a gift without written permission. If you would rather the donation stayed private, say so on the form and that is the end of it.
Several cars in the same year
The IRS groups similar items donated within the same tax year for the reporting thresholds. Three cars at $4,000 each are one $12,000 donation of similar property for that purpose, which puts you above the appraisal and Section B threshold even though no single car is close to it.
This catches people out, and it is the sort of thing to raise with your accountant before the first car leaves rather than after the third one has. If you are planning to donate more than one vehicle, tell us on the form so the paperwork is right from the start.
Questions on significant cars
Do I need an appraisal?
Only if you intend to claim more than $5,000. Below that, the Form 1098-C we send you after the sale is your substantiation. Remember that similar vehicles donated in the same year are grouped when measuring that threshold.
Will an appraisal get me fair market value?
Almost certainly not, and anyone telling you otherwise is not being straight with you. When we sell the car your deduction is the gross proceeds of the sale. The appraisal is required paperwork above $5,000; it is not the deduction.
Can I say where the car must be sold?
You can tell us, and we want to hear it. We cannot hand you control of the sale. Beyond the practical point that we own the car, a retained right over how it is sold can put your deduction at risk.
Who pays for the appraisal?
You do. Towing, transport, title work and the IRS filing on our side are covered by Giving Center. A qualified appraisal is the donor's expense and the donor's choice.
Can the donation stay anonymous?
Yes. We publish nothing about a donor or a car without written permission.
Giving Center does not provide tax, legal or financial advice. Donations are deductible to the extent allowed by law. See IRS Publication 526, Publication 561 and Publication 4303, and consult a tax professional.